Can I get an SR&ED loan if my bank has me in special loans?
A strong SR&ED claim was declined because the bank had the company in special loans. Why that usually ends it, and what to do instead.
In practice, no. Once your bank has moved your file to special loans or put you in default, an SR&ED lender will almost always have to decline, no matter how strong your claim is.
This one is for founders and CFOs whose numbers are slipping but who are still in good standing with their bank. That's the window that matters.
The situation
A consulting services company applied to us for an SR&ED loan. It had been operating for the better part of a decade and, for most of that time, it made money. Then AI changed its industry. Clients expected the same work for less, margins compressed, and there was simply less business coming in. Revenue was declining and the company was running at a loss.
The SR&ED side looked good. The claim was in the $200,000 to $400,000 range, expected to come in a little smaller this year, and an experienced consultant had prepared it carefully. Underwriting went well. Declining revenue and negative earnings don't rule a company out on their own.
Then we reached a standard question on our application: are you in good standing with your senior lender? The answer was no. Their bank had moved them to special loans, the group that manages accounts the bank is worried about.
How we looked at it
There were two problems, and either one would have been enough.
The first is security. We take first priority security on the SR&ED claim, and when a company has a bank, we sign an intercreditor agreement so everyone knows who gets paid from what. A bank's special loans group is trying to protect its position, not hand part of it to someone else. In my experience, a bank with a borrower in default will almost never agree to let another lender go first on any asset, the SR&ED refund included.
The second problem is worse. Even if the bank had agreed, it could still push the company into insolvency at any time. As a junior lender, we'd have no way to stop that. The refund could land in the middle of a process we don't control.
Timing makes that risk real. We most often lend against accrued SR&ED and the CRA generally processes a claim in about 60 days if it isn't reviewed, and about 180 days for a refundable claim under review (CRA: After you claim). That's a long time to hope a bank in workout mode stays patient.
So the real question was: how does this company get out of the hole? Looking at the financials, I couldn't see a clear path. Revenue wasn't down because of a slow quarter. The business itself had changed.
The decision
Declined. The claim was good and the rest of the file was clean, but the chance of insolvency before the refund arrived was too high. We don't lend into that position, and I'd rather say so early than drag a founder through weeks of diligence.
A refund advance buys time. It doesn't fix a business, and it can't outrun a bank that has already decided to act.
What to do instead
- Arrange SR&ED financing while you're still in good standing. If your numbers are slipping, talk to an SR&ED lender before the bank moves your file. Part of an advance could even go toward paying the bank down to keep you out of default, subject to the bank agreeing to the intercreditor terms. Remember it's still a loan, and it's owed even if CRA reduces your claim.
- Look at other non-dilutive options. Grants and other government incentive programs don't add another lender to an already crowded table.
- Raise equity from existing or new shareholders. It costs you ownership, and it's harder to raise from a weak position, but it may be the realistic option once new debt is off the table.
Frequently Asked Questions
Can I get an SR&ED loan if my bank has me in special loans?
In practice, rarely. Once a bank has moved a file to special loans or put the company in default, an SR&ED lender will almost always decline, even when the SR&ED claim itself is strong.
Why do SR&ED lenders decline companies in default with their bank?
Two reasons. A bank in default mode will almost never give another lender priority on the SR&ED refund, and even if it did, the bank could push the company into insolvency before CRA pays the refund. A junior lender can't stop that process.
What can a founder do instead of SR&ED financing when in special loans?
Ideally, arrange SR&ED financing before the bank moves the file, possibly using part of it to pay the bank down. Once in special loans, look at grants and government incentive programs, or raise equity from existing or new shareholders.
Related articles
Related pages
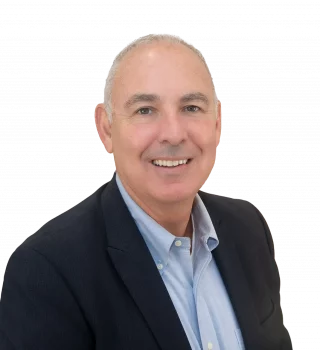
Garron Helman - CEO
Garron Helman is the founder of Grow Financial, a Canadian lender providing SR&ED financing to innovative businesses. With over 15 years of experience in financing Canadian companies, including as a Partner at Espresso Capital and founder of Venbridge, Garron understands the challenges of funding growth. He writes about SR&ED, non-dilutive financing, and helping founders access capital without giving up equity.
This article is for general information only and isn't tax, legal or financial advice. SR&ED eligibility is determined by the Canada Revenue Agency. All financing is subject to Grow Financial's credit approval and loan documentation. Speak with a qualified adviser about your situation.